From Kiplinger · · 3m
Your will won't fix an outdated beneficiary form
The paperwork nobody reviews decides where your 401(k) and life insurance actually go.
In brief
The paperwork nobody reviews decides where your 401(k) and life insurance actually go. Beneficiary designations override your will, so check every account by name at least once a year. Originally reported by Kiplinger.
A will doesn't cover everything
Retirement accounts, life insurance and some bank and brokerage accounts pass straight to the person named on the form, no matter what your will says.
“Creating a will is an important part of estate planning, but it doesn't necessarily determine who receives every asset you own.”
The name may be stale
Whoever you wrote down when you opened that workplace 401(k) is still the one who inherits it, even if that was three jobs and one marriage ago.
Most parents haven't done it
A Morning Consult survey for Kiplinger found only 36% of parents had named beneficiaries on retirement accounts or life insurance. Another 30% had no formal arrangements at all.
“just 36% of parents surveyed had designated beneficiaries on retirement accounts or life insurance policies”
Know which accounts count
401(k)s, traditional and Roth IRAs, life insurance policies, annuities, and transfer-on-death or payable-on-death bank and brokerage accounts all carry their own designation.
TOD and POD skip probate
These designations move money in certain bank and brokerage accounts directly to a named person. Rules vary by institution and by state, so check yours.
Workplace plans favor spouses
Many employer-sponsored retirement plans require your spouse to be the primary beneficiary unless they sign a waiver. IRAs and life insurance give you more freedom.
Verify, don't remember
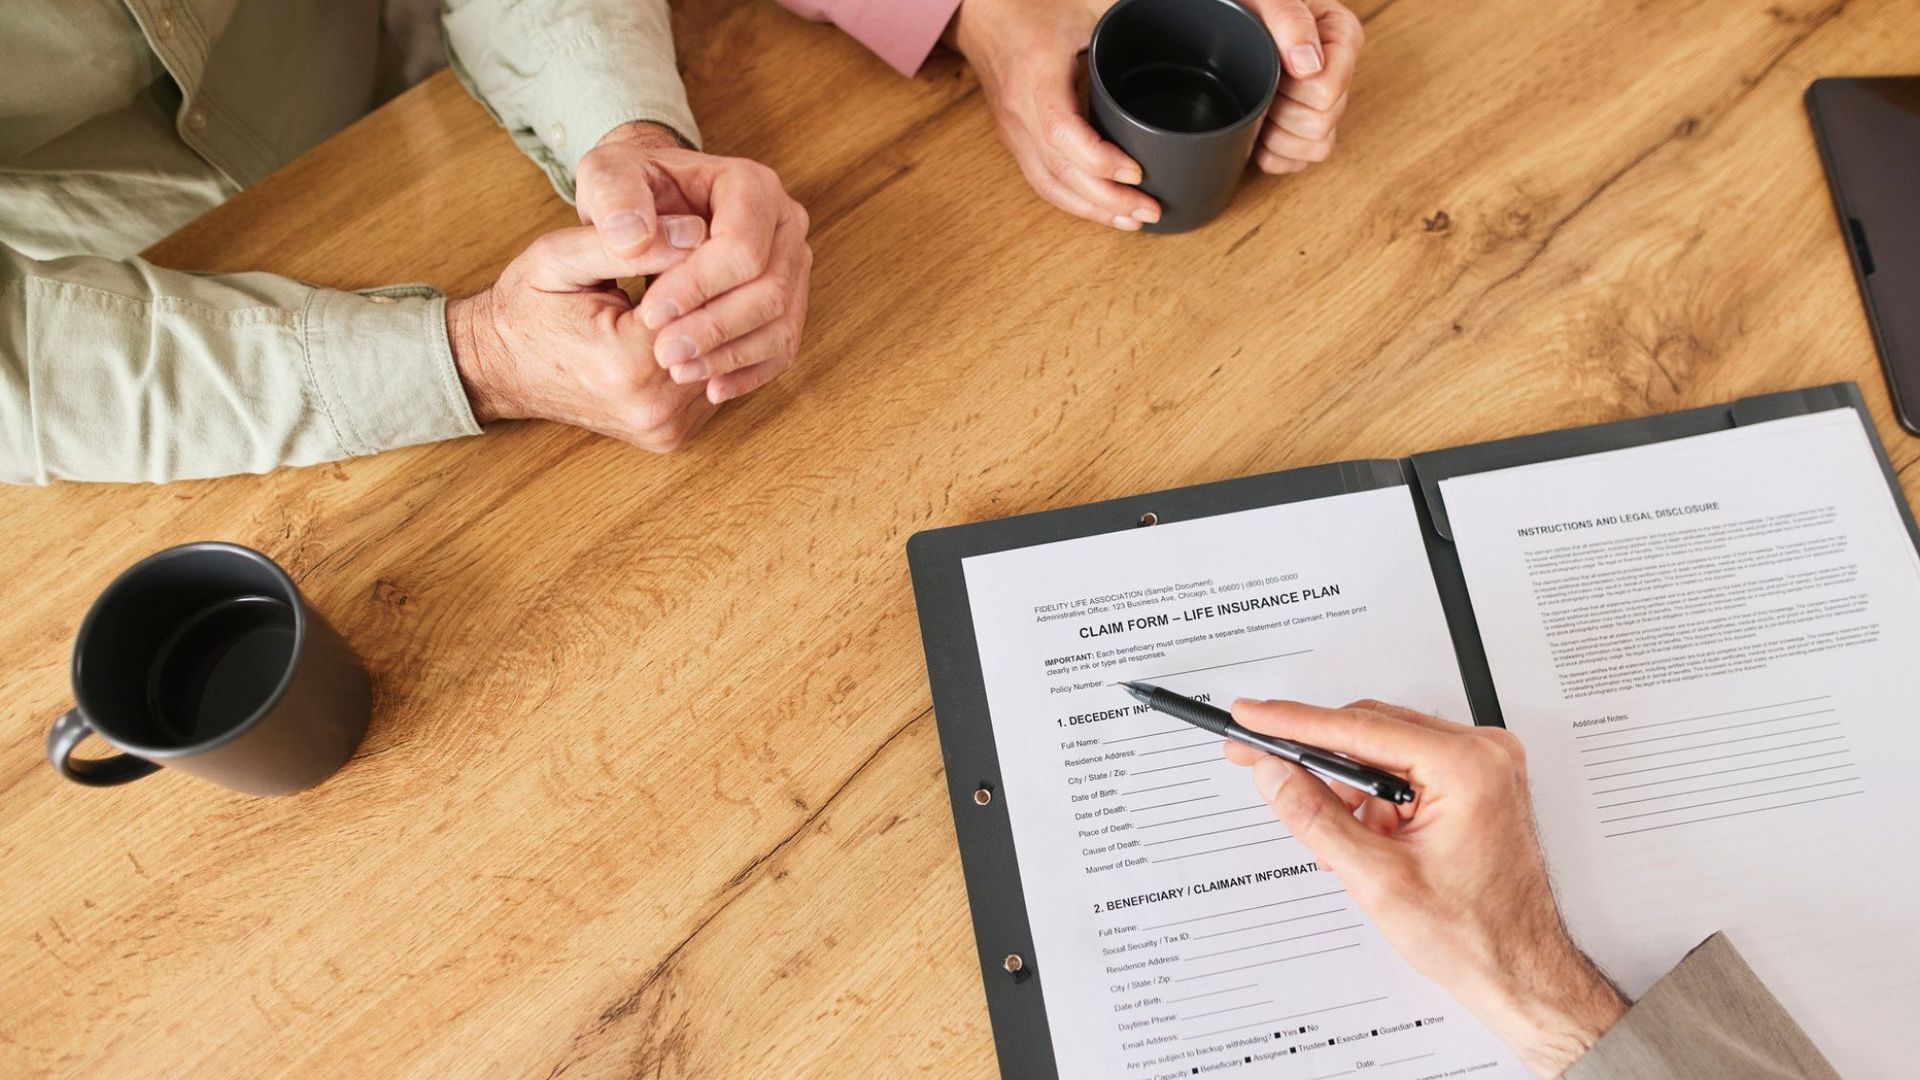
Log in to each provider or call the plan administrator, insurer or brokerage. Confirm what the institution actually has on file, not what you recall signing.
“Don't rely on your memory of filling out a beneficiary form years ago.”
Check the backup too
Look at your contingent beneficiary, the person who inherits if your first choice dies before you, can't be found or turns the money down. Hunt for accounts with nobody listed.
Transfers can drop the form
Moving an account to a new firm can leave the designation behind. FINRA recommends double-checking beneficiary information after any transfer.
Events that demand a review
Marriage, divorce, remarriage, a death, a birth or adoption, estrangement, a beneficiary who develops a disability, or a big swing in your wealth.
The divorce trap
You divorce, remarry, and rewrite your will to leave everything to your new spouse. The old retirement account still names your ex, and that form wins.
“the beneficiary designation on the account generally takes priority over what your will says”
Look at the whole picture
Line up retirement accounts, insurance, real estate and your will together. You may find one child inheriting a large account while another gets far less.
Say it out loud
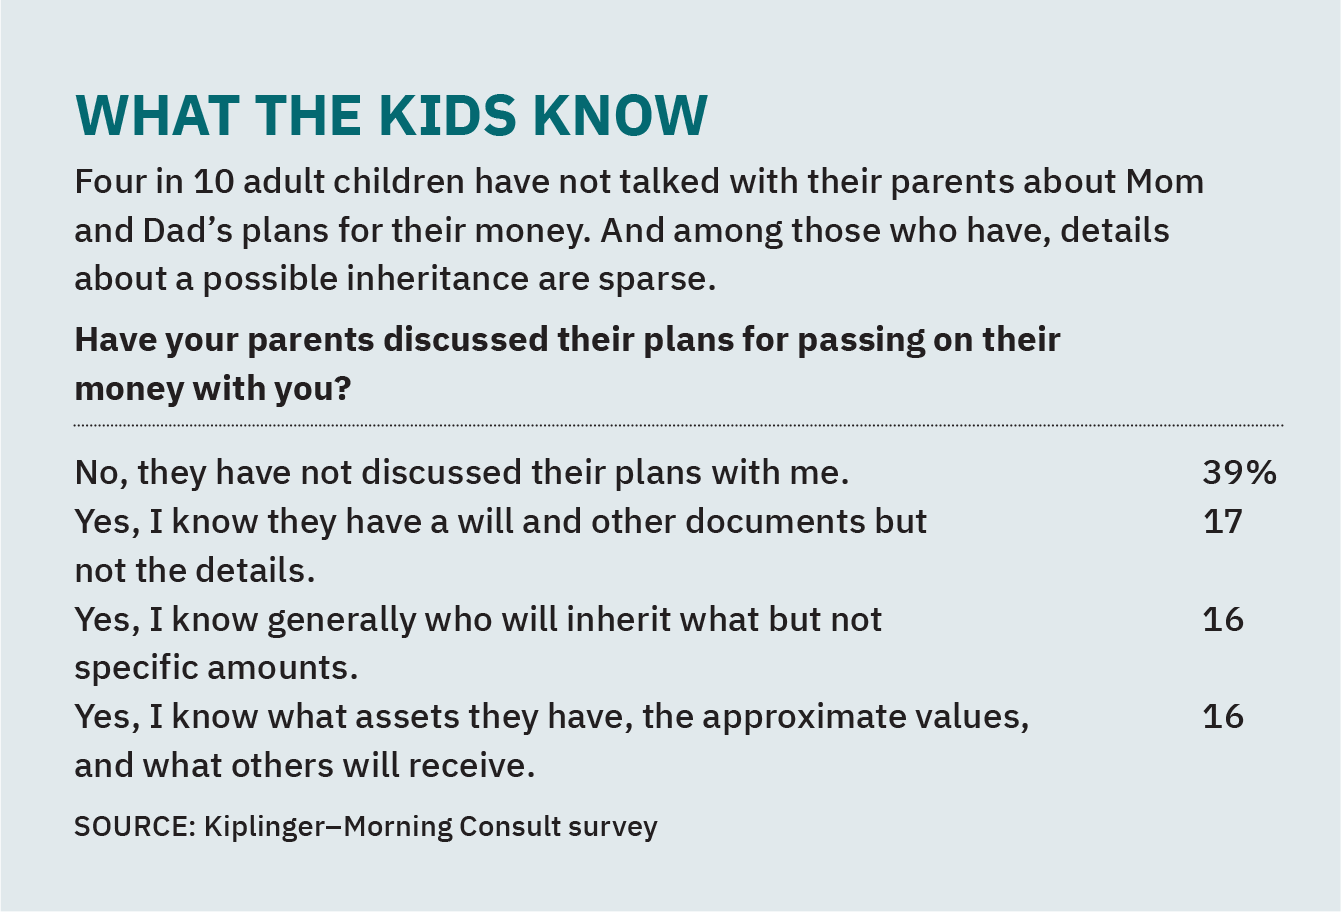
Two in five families have never talked about inheritance. Even a short conversation about your plans and where the documents live saves your family later.
“two in five families have never discussed inheritance”
Make it an annual habit

List every account with a designation, check primary and contingent names, record what you changed and when. Repeat yearly and after any big life change.
The headline
Beneficiary designations override your will, so check every account by name at least once a year.