From MoneyWeek · · 3m
Vistry: the market's most hated housebuilder
Six profit warnings, an 80% share price collapse, and a £350m government cheque that might change the story.
In brief
Six profit warnings, an 80% share price collapse, and a £350m government cheque that might change the story. Vistry is a genuine deep value bet: trading at half the sector average and 50% below book value, but only worth it if you believe the new CEO can fix years of cost and land mistakes. Originally reported by…
An 18% jump in one day
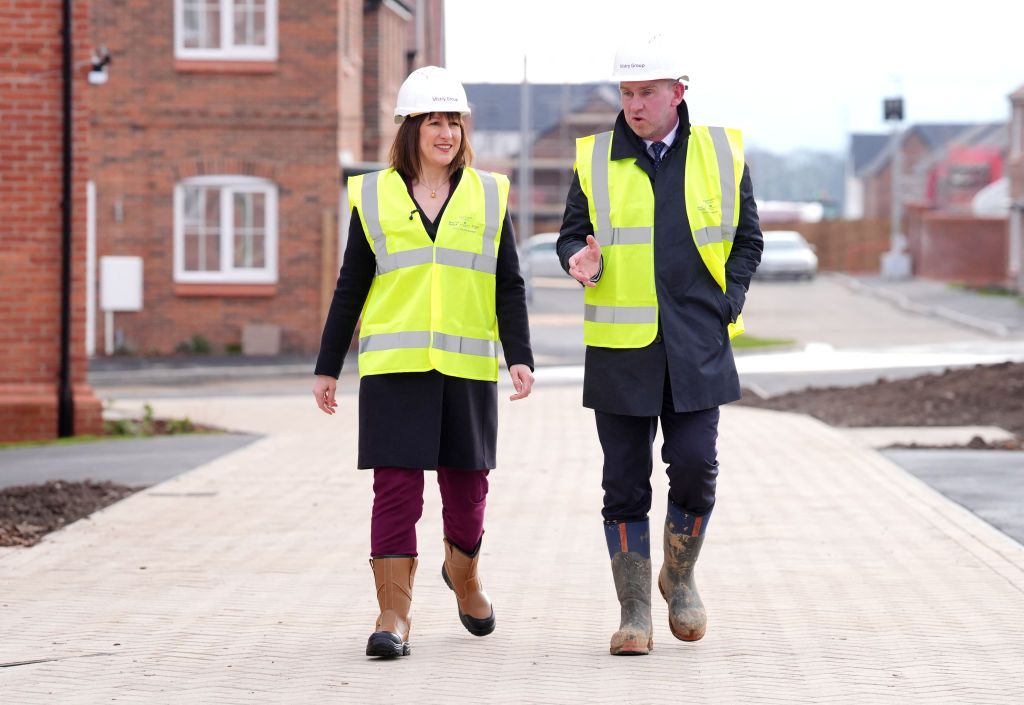
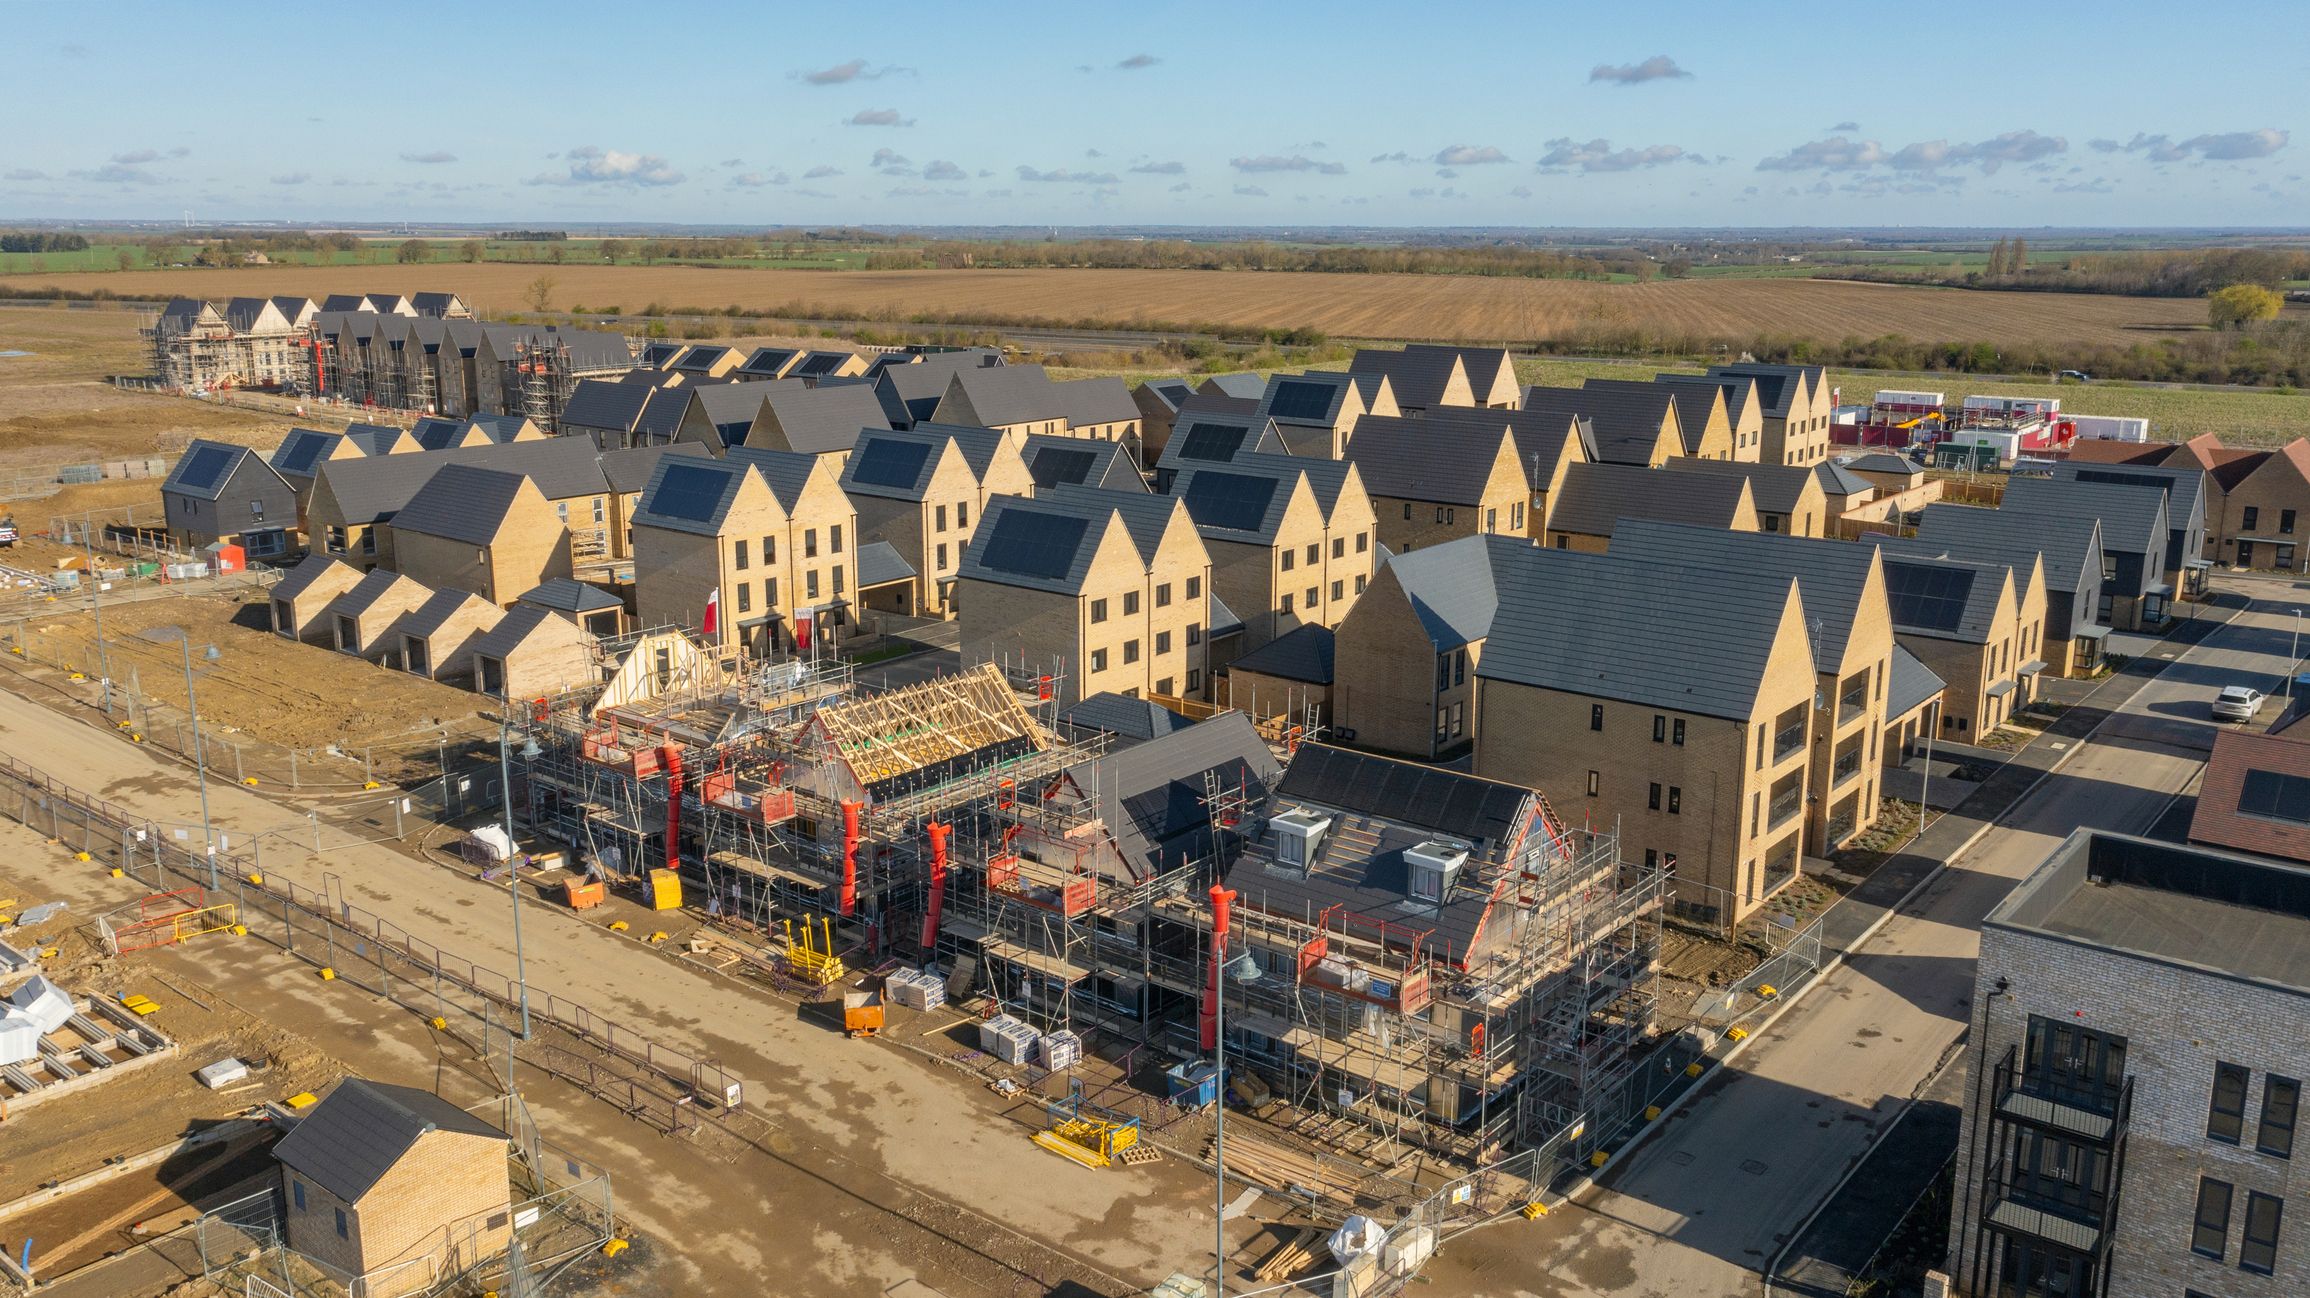
Shares in Vistry leapt 18% on 25 August when the Kent-based builder landed £350 million from the government's £39 billion social and affordable homes programme.
Bigger money per home
The award beat the previous programme's £278 million and was the largest possible in the first £9.5 billion round. Funding per home rose from £79,000 to £116,000, covering over 3,000 affordable homes.
The Labour building play
Vistry delivers around 15% of the UK's social and affordable homes, making it one of the purest ways to bet on the government's drive to get Britain building.
“investors don't seem to be pricing in any growth”
Built by dealmaking
Greg Fitzgerald turned Bovis Homes into Vistry through acquisitions: £1.1 billion for Galliford Try's housing arm in 2020, then £1.3 billion for Countryside Partnerships in 2022.
Partnerships over private sales
The strategy was to build for councils and housing providers rather than private buyers, which looked smart as politicians swung back toward public-sector housing.
The £60 million bonus row
US hedge funds Abrams Capital and Browning West, holding over 20%, wanted to pay Fitzgerald up to £60 million if shares hit £18. The remuneration committee said no, but trust was already gone.
Six profit warnings
Three landed in quick succession in late 2024, including one on Christmas Eve. Each blamed costs coming in higher than expected.
March and the 20% drop
Shares fell more than 20% in a single day when Fitzgerald's retirement came alongside a cut to the year's outlook. By July, guidance was scrapped entirely.
Losses on both sides
Vistry told investors to expect a pre-tax loss of about £30 million for the first half of 2026, on top of the £40 million loss in the first half of 2025.
Most shorted on the market
The shares are off 80% from their August 2024 peak, despite a 20% bounce from June's multi-decade low. No London-listed company carries more short interest.
Land bought in a hurry
Reports say Fitzgerald pushed buyers to grab any land going, some of it unusable. New CEO Adam Daniels must sell it, and buyers who smell urgency will squeeze him on price.
“Buyers know the company is in a rush to sell and they will push a hard bargain.”
Cheap if the numbers land
Panmure and Peel Hunt see profit rebounding hard by 2030. On their forecasts the stock trades at 5.5 times 2027 earnings, with book value of 625p, 120% above the price.
“if Vistry can prove to the market it's back on track, the shares could double”
What matters most
Vistry is a genuine deep value bet: trading at half the sector average and 50% below book value, but only worth it if you believe the new CEO can fix years of cost and land mistakes.